Original author: Arthur Hayes, BitMEX Lianchuang
Original compilation: Golem, Odaily Planet Daily
Editor's note: In his latest article "Yen-quake", Arthur Hayes believes that the yen's exchange rate against the US dollar is about to appreciate. The most likely path is for the Japanese government to use the FIMA mechanism to mortgage its treasury bonds to the Federal Reserve for repurchase financing, borrow US dollars, and then use these US dollars to buy Japanese yen. Arthur Hayes also said that this will also lead to a surge in US dollar liquidity, which will in turn increase the prices of assets such as Bitcoin and physical gold. He believes that in addition to Bitcoin and Ethereum being undervalued at this stage, ENA is also expected to rise 5-10 times in the next few months.
Arthur Hayes revealed that his "bullets" have not been exhausted yet. What must now wait is for Warsh to convene a subcommittee and modify the FIMA rules to open the way for Japan to use the FIMA mechanism to promote the appreciation of the yen. Odaily Planet Daily compiles the core content of the full text as follows, enjoy ~
Over the past decade, the yen has weakened and even become extremely weak, driving global asset markets higher. But like all good things that benefit wealthy financial asset holders, this must eventually come to an end. The yen is the most undervalued currency in the world and a bone of contention between China and the United States, as well as ordinary Japanese voters. There are three ways to solve the yen conundrum, but the U.S. Treasury Department and Japanese politicians only favor one of them.
I'll explain how each method of making the yen appreciate works, and summarize why the last one is the preferred option. I then explore how this third option might be implemented at the political level. Finally, I will elaborate on why Bitcoin and cryptocurrencies will explode as USD liquidity surges (I know this is why you read my “human bullshit”).
The three options are as follows:
1. The Bank of Japan (BOJ) raises interest rates sharply, thereby eliminating the interest rate differential between the U.S. dollar and the yen (at least in terms of short-term interest rates);
2. The government lobbies domestic institutions and public institutions (such as the Japanese Government Pension Investment Fund GPIF) to change investment strategies, sell overseas assets and buy domestic assets;
3. [Preferred option] Japan’s Ministry of Finance (MOF) mortgages its holdings of U.S. Treasury bonds to the Federal Reserve in exchange for U.S. dollars through repurchase (repo), and then sells U.S. dollars and buys Japanese yen in the foreign exchange market.
Before going into the details, all you "degens" in the currency circle should ask yourself: Why are we discussing the appreciation of the yen at this time? Over the past few decades, countless people have asserted that the yen was about to appreciate and end the global carry trade. Two weeks ago, senior monetary policy officials from the United States and Japan carried out a joint currency manipulation, which of course the officials euphemistically called an "intervention." If the same behavior is done by ordinary people, it is "collusion" and "conspiracy." But when the operator becomes a country, the name is completely different.
U.S. Treasury Secretary Bessent has declared that he wants the Federal Reserve to increase the counterparty limit on the FIMA repurchase facility so that Japan's Finance Ministry can use its huge asset reserves to defend the yen's exchange rate. Japan's Ministry of Finance also announced that it is joining forces with the United States to try to lower the exchange rate of the U.S. dollar against the Japanese yen. The authorities have made it clear that they will change the global monetary landscape, so we must take it seriously.
Three options for a stronger yen
Options 1 and 2 are simply unworkable because none of the parties involved can afford the political and economic consequences of departing from established policies since the 2010s.
Option 1: The Bank of Japan raises interest rates
Currency trades tend to be based on interest rate differentials, and the U.S. dollar yields 2.75% more than the Japanese yen. Borrowing Japanese yen, converting it into U.S. dollars, and buying U.S. Treasuries provides a positive carry yield. Therefore, according to the no-arbitrage principle, the dollar-yen exchange rate must rise (i.e., the yen depreciates against the dollar) to offset this interest rate differential. The most direct way to make the yen appreciate against the US dollar is for the Bank of Japan to raise interest rates to bring them in line with central banks in other countries that have raised interest rates after the COVID-19 epidemic.
To understand the conundrum the Bank of Japan faces in raising interest rates, it’s important to remember that the Bank of Japan has become the largest holder of these “junk” JGBs as a result of more than a decade of yield curve control (YCC) policy, which involves printing money to buy bonds to limit the yield on 10-year Japanese government bonds.
Once interest rates rise, bond prices fall; the lower bond prices fall, the greater the BOJ's unrealized losses. Unlike ordinary investors, the Bank of Japan, which can print unlimited money, can withstand unlimited yen losses. However, once the Bank of Japan prints money on a large scale and causes the world to lose confidence in the yen, and then no longer accepts the use of yen to settle transactions such as oil, food, medicine, etc., the situation will become critical.
Although it has not yet reached this point, the Bank of Japan must face up to this potentially catastrophic prospect. It is precisely because of the fear of seeing losses on its balance sheet that the Bank of Japan is hesitant to raise interest rates only slightly and watch the market sell off long-term Japanese government bonds. As a result, the yen continues to depreciate, and the inflation caused by imported energy has seriously impacted the foundation of Japanese society.
Politicians don't want the Bank of Japan to raise interest rates because they have to finance the fiscal deficit by issuing Japanese government bonds. If yields rise, debt servicing costs will also increase, which will reduce their ability to use various government subsidies (usually consumption tax breaks) to "buy off" ordinary people.
If the Bank of Japan quickly raises interest rates and causes the yen to appreciate, thereby pushing up the exchange rate volatility of the U.S. dollar against the yen, then all investors who use yen financing to buy global stocks or bonds will be forced to close their positions.
Remember July 2024? At that time the yen exchange rate rose from 160 to 140 in just a few trading days. I have written two articles on this in depth, but in short, new Bank of Japan Governor Kazuo Ueda unexpectedly announced an interest rate hike and promised further increases in the future. The market panicked, and speculators who were short the yen and long other financial assets liquidated their positions. There were rumors at the time that PMs under several hedge funds were forced to leave because of this, just like Kenny G ended the AI stock god Leopold.
The yen hit 140 at the time, and the Nasdaq 100 and Nikkei both fell more than 10%. The Bank of Japan panicked and announced on August 12 that it would take "market conditions" into account when assessing the path of future rate hikes, effectively meaning that future rate hikes have been put on hold. As soon as the news came out, the Japanese yen weakened, and the stock market bottomed out and resumed its upward trend.
Compared with other central banks, the Bank of Japan has moved too quickly in normalizing interest rates and is therefore unable to withstand the severe market pressures it triggers.
Option 2: "Japan Inc." sells overseas assets to return Japanese yen
I define "Japan Inc." as corporations and the public sector that hold financial assets.
Albert J. Alletzhauser tells an interesting anecdote in the book "The Nomura Empire: Inside Japan's Legendary Financial Dynasty": After the stock market crash in 1987, Japan's Ministry of Finance instructed Nomura Securities to buy U.S. stocks to support the market. As a private company, Nomura had no obligation to obey this directive, but Japan is a society that values conformity and collective action, so Nomura ultimately implemented it.
Many times, the highest goal of a business is not shareholder return, but achieving full employment and safeguarding "national honor" (whatever that may be). If the government advises private companies and individuals to sell overseas assets (mainly U.S. stocks and U.S. bonds), sell U.S. dollars for Japanese yen, and repatriate the funds, "Japanese companies" will have to comply.
The indicator that can best release the signal of "Japan's capital flow back" is the movement of Japan's largest pension fund, the Japanese Government Pension Investment Fund (GPIF). The GPIF is governed by a bureaucratic board whose members are appointed by various government departments.
In 2014, in order to cooperate with the large-scale money printing policy under "Abenomics", the then prime minister spent several years changing the head of the GPIF, prompting him to vote to increase the allocation proportion of overseas stocks and bonds in the investment portfolio. This is critical because GPIF manages a portfolio of $1 trillion to $2 trillion. When their investment strategy changed in October 2014, it started an unstoppable wave and they began selling yen for dollars and buying U.S. stocks and bonds.
This move created a structural yen seller, which reassured speculators that they could use the cheap yen to finance a variety of financial assets without worrying about the yen appreciating when loans were rolled over or repaid.
I mention GPIF because the head of Japan's Ministry of Finance, Mr. Katayama, recently declared that, in his view, it was time to adjust GPIF's investment strategy to favor domestic securities over foreign securities. However, bureaucrats within GPIF are not buying it and have publicly stated that they will insist on acting in the best interests of policyholders. Obviously, given that they are adherents of "Abenomics", they will never support a shift in investment focus to Japanese domestic securities.
Just as Abe took control through personnel arrangements between 2012 and 2014, Prime Minister Takaichi must do the same. For us investors, the signal is clear: GPIF's investment strategy will eventually change, forcing it to sell hundreds of billions of dollars' worth of foreign securities, while the repatriation of funds will push the yen higher.
Although this process will take several years to complete, it is enough to worry Bessant, because it means that "Japan Inc.", one of the largest holders of U.S. securities, will change from a buyer's position to a seller's position. This would destroy the stock and Treasury markets that "His Highness the United States" relies on to prop up his profligate empire. However, precisely because "His Royal Highness the United States" guarantees Japan's national security, "Japan Inc." cannot actually sell off its U.S. assets.
The above is not new information. Everyone believes that the yen exchange rate is low, and both the United States and Japan also hope that the dollar will appreciate against the yen. But if the USD/JPY exchange rate falls from 160 to 90 (fair value based on purchasing power parity), neither side can afford the losses.
And from the moment Trump's close friend, "Weasel" Warsh (who does look like a weasel and behaves equally cunningly and sinisterly), became chairman of the Federal Reserve, the third option was allowed to be launched.
The 2026 "Treasury-Fed Agreement" remains solid and in effect; in addition to using reverse repurchase facilities and policy rates below nominal growth to directly fund short-term Treasury bonds issued by Bessant, Warsh also has the authority to implement "Option Three" to once and for all adjust the USD/JPY exchange rate to the level needed to rebalance the global economic system.
Option 3: Loan from the United States
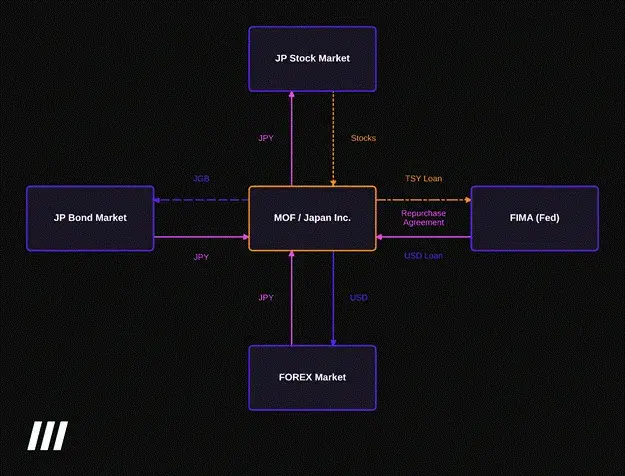
Bessent made it very clear that the Ministry of Finance and Japanese companies should not sell U.S. securities to raise the funds needed to boost the yen. Instead, they should use the FIMA mechanism to mortgage their holdings of government bonds to the Federal Reserve for repurchase financing, borrow U.S. dollars, and then use these U.S. dollars to buy Japanese yen.. There was a slight flaw in his plan, which I'll get to later, but the box-and-arrow diagram above captures exactly this process. Let’s sort out the process again:
1. Japan’s Ministry of Finance purchases government bonds and obtains U.S. dollar loans from the Federal Reserve’s FIMA mechanism;
2. Japan’s Ministry of Finance sells U.S. dollars and buys Japanese yen in the global foreign exchange market;
3. The Ministry of Finance of Japan will reinvest these yen funds domestically and buy Japanese government bonds and stocks.
The main impacts of this policy include:
· The Fed provides U.S. dollar funding through money printing, and its balance sheet will expand in parallel with the increase in the outstanding balance of FIMA repurchases;
· The decline in the exchange rate of the US dollar against the Japanese yen means that the Japanese yen appreciates;
· Affected by the purchase of Japanese bonds by the yen, Japanese bond yields fell;
· Japanese stocks rose on yen buying.
Who is the "taken advantage of"?
1. U.S. taxpayers: Japan owes U.S. taxpayers a sum of money that, for political reasons, will never be repaid. Because this is purely an act of printing money, it will trigger inflation at the level of financial assets and physical commodities. The United States cannot demand repayment of this loan by using its forward operating bases in the Asia-Pacific region against China and Russia.
2. Anyone who is short the yen: they must close their position as soon as the trend becomes clear. This is less of a problem as USD/JPY volatility will fall, allowing the yen carry trade to unwind in an orderly manner over a multi-year period.
Why has option three not been implemented yet?
As it stands, the FIMA facility has a $60 billion cap on outstanding loans per counterparty. In the latest effort to manipulate the dollar-yen exchange rate, the U.S. Treasury Department and the Japanese Ministry of Finance invested more than $100 billion, but only pushed the yen to appreciate by 5%, and the appreciation effect lasted only a few trading days. To take advantage of the FIMA mechanism, this cap must be removed entirely and the scope of eligible counterparties expanded to include large Japanese companies and quasi-public investment institutions such as GPIF.
Who is managing the FIMA mechanism? During the COVID-19 pandemic, the Federal Open Market Committee (FOMC) delegated authority to adjust the way the FIMA mechanism operates to the Subcommittee on Foreign Currency. Voting members of the committee include Warsh (FOMC Chairman), Williams (FOMC Vice Chairman and New York Fed President), and Jefferson (Vice Chairman of the Board of Governors). The committee convenes meetings at any time as the situation requires. It neither publishes meeting minutes nor voting records. The outside world can only learn the results of its decisions.
So, will the committee do the bidding of Bessant? The answer is absolutely yes.
Trump and Warsh communicate frequently, and given that Bessant has clearly articulated how to reshape the global economic balance by adjusting the dollar-yen exchange rate, Trump is clearly fully supportive of this. Therefore, Trump and Bessent will deliver instructions to Warsh. Wash has previously proven himself to be a slippery and bluffing "paper tiger." Under Williams' stewardship of the New York Fed, the Fed's balance sheet continues to expand through RMP.
Warsh, who has said he listens to the market when setting policy, declined to raise rates at the July meeting when the market was clearly demanding a rate hike as the two-year Treasury yield was more than 0.5% above the federal funds effective rate. Rather than immediately institute sweeping and drastic changes to the way the Fed operates, Warsh established five task forces to study how and why the Fed should make changes. I'm afraid that by the time these working groups come up with any recommendations, "Gordo" will show up long ago.
(Odaily note: The allusion comes from "Waiting for Godot", Arthur Hayes is satirizing the efficiency of the five working groups -).
As a result, Warsh has proven in a short period of time that he is just another partisan politician who only does what his boss tells him to do. This is just like his predecessor, the submissive, spineless "softie" Powell, and the earlier "garden dwarf grandma" Yellen (who turned into a "bad girl" after she was promoted to Treasury Secretary).
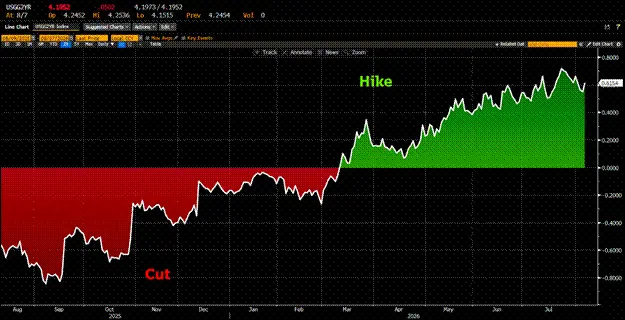
The difference between the two-year Treasury bond yield and the federal funds effective rate
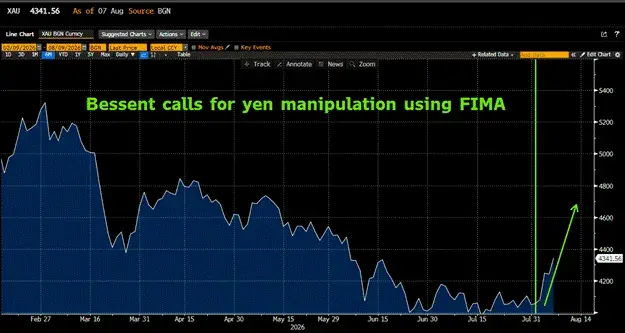
I don't know when Warsh will convene a subcommittee and announce changes to the FIMA mechanism that would allow unfettered money printing to manipulate USD/JPY lower, but I'm sure it will happen. In fact, I'm betting this will happen and am continuing to increase my exposure to assets that reflect the impact of another massive expansion of the Fed's balance sheet. These assets include Bitcoin, physical gold, and shares of gold miners.
The implementation of the third plan will push up the price of Bitcoin
As long as the Fed prints more money, the price of Bitcoin will rise. So, is this trick of FIMA enough to become a huge "pump", in which huge funds worth trillions of dollars are injected into it, thus pushing up the prices of the assets we hold?
For now, we are only focusing on Treasury holdings, as Treasuries are the only assets that qualify as collateral under FIMA. Things may change in the future, but let’s focus on the assets that the tool currently allows. The two largest entities holding treasury bonds are the Japanese government and GPIF. The Japanese government holds $1.143 trillion in U.S. Treasury bonds and GPIF holds $230 billion, for a total of $1.373 trillion.
This is a considerable amount. To help understand the scale, we can consider what happened during the COVID-19 pandemic. The Fed printed about $4 trillion in currency, as evidenced by the expansion of its balance sheet between 2020 and the end of 2021.
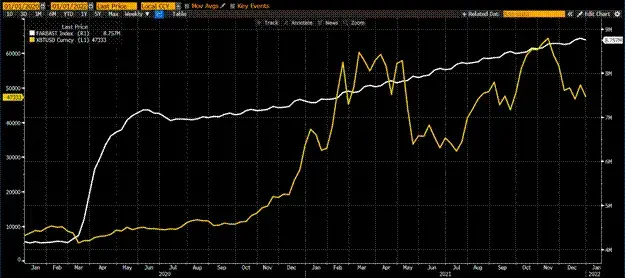
There is a very clear correlation between the growth in the size of the Fed’s balance sheet (white curve) and the surge in Bitcoin’s price (gold curve). I speculated in a previous article that the construction of the AI field is entering a phase of capital waste. This assertion is crucial because the Trump administration hopes that this liquidity can be used to drive domestic AI capital expenditures in the United States, rather than be used to drive up cryptocurrency prices.
But I believe that extending credit to AI companies that are unable to achieve positive returns on capital at this time (whether they are very large-scale cloud service providers that invest heavily but cannot truly make a profit, or those US AI labs that cannot make profits at the "Chinese market Token price") is essentially wasteful; and the rise in Bitcoin prices exactly reflects this unproductive use of capital.
The recent sharp rebound in gold prices from periodic lows has sent us a signal: the market would rather channel the coming torrent of U.S. dollar fiat currencies into monetary and financial assets than give money to Ultraman's "money-burning machine" OpenAI, or Musk's illusory space data centers.
Altcoin carnival is coming, be optimistic about ENA’s 5x return
I know you all want to know what exactly we are doing at Maelstrom, but to build investment conviction, you must first understand the macro backdrop.
As I said before, when Bessant speaks, I listen. If he has any special skill, it is currency manipulation. Just go to Google and search for his glorious resume working with Soros, and you will understand. Carrying out this monetary "sleight of hand" requires neither the approval of elected politicians nor the nod of those whose terms are about to expire and face public confirmation hearings in the Senate. Just convene the usually sleepy "Foreign Exchange Subcommittee" to change the rules of the game, and it can trigger a blowout of dollar money printing.
When I saw the news about Bessant’s call for reform of the FIMA regime, I immediately had a bullish gut feeling.Every macro analyst I follow believes this signals a major turning point for USD/JPY. You have to plan ahead because they are serious about it this time.
Printing money is a political decision made to address an unsustainable economic reality. Politics are always complicated, but in the current situation, the Trump administration's intentions are clear: it wants you to log into your brokerage account and buy financial assets. That's why Bessant sent a clear signal to anyone who would listen about where the printed money would begin to spread. I'm listening and will do my "duty" - Buy in.
We already hold a lot of Bitcoin, so the next question is who will do better?
Although this is not an AI stock recommendation article, if you are interested in that stuff, you can still buy the bottom. "Leopold Low" has provided you with an excellent opportunity to enter AI-related assets.Speaking of cryptocurrencies, the large-cap potential stock that has not yet exploded is ETH, which is the only mainstream currency that has failed to break through all-time highs in the 2025 market; in addition, Ethereum will become a security layer for RWA assets.
Next up is Ethena (ENA), an altcoin that is at its trough but is poised to easily post 5-10x gains.
One issue with Ethena is the lack of a buyback mechanism, however, this can be ignored considering that it is still the sixth most circulated USD stablecoin. The problem with ENA is that the yield on holding USDe is barely higher than on U.S. Treasuries as Bitcoin’s basis returns disappear due to the currency’s falling price. It is simply not cost-effective to bear the counterparty risk and smart contract risk of a centralized trading platform in order to hold pledged USDe.
Because of this, its circulating supply has dropped by 75% from its peak, and the price of the ENA token has also fallen by more than 90%. But even a small increase in U.S. dollar liquidity in the future could drive Bitcoin prices higher, thereby driving up basis yields and leading to large inflows into USDe. It wouldn't take much for ENA to get out of the downturn, so it might be a "speculative" option worth considering for a quick 5x in the coming months.
I haven't run out of bullets yet, we have to wait for Wash to convene a subcommittee and change the FIMA rules, keep an eye on it, it might happen when no one is looking.However, gold and the USD/JPY exchange rate should start to fluctuate before the policy is announced. After all, those big investors with close ties to the Trump administration are likely to rush to plan ahead before the news is released. This situation is seen frequently in other asset classes, and the gold and foreign exchange markets are no exception.
In short, the days of the "cheap" yen are coming to an end.