Author: Zhang Yaqi
Federal Reserve Chairman Warsh is about to make an appearance at the Jackson Hole annual meeting, which the market views as the most critical risk event for the current trend of U.S. bonds and the U.S. dollar. As the Treasury Department ramps up its repurchases of long-term Treasury bonds and the U.S. dollar continues to be under pressure, whether Warsh can send a clear anti-inflation signal will directly determine the direction of the 30-year U.S. bond yield.
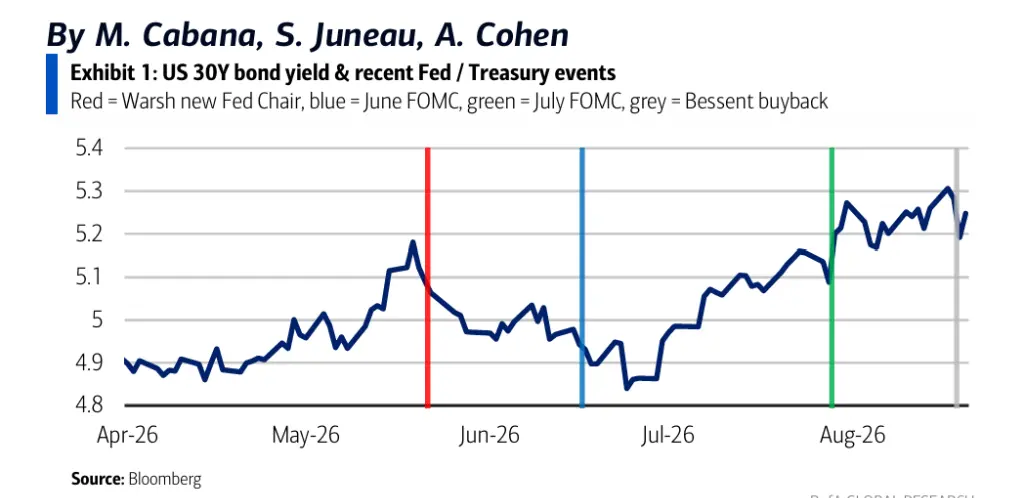
According to the Chase Trading Desk, according to a research report released by Bank of America on August 24, market expectations for Warsh's speech have quietly changed - the continued rebound in the bond market is forcing the Federal Reserve Chairman, who has always resisted forward guidance, to adjust his communication strategy. Bank of America strategists Mark Cabana, Stephen Juneau and Alex Cohen warned,If Warsh fails to clearly clarify the inflation outlook and monetary policy response function, the 30-year U.S. Treasury yield may quickly test 5.5% or even higher, and the U.S. dollar will also face a new round of downward pressure.
Barclays economist Marc Giannoni and others also pointed out in a report released on August 21 that although Warsh is unlikely to provide specific guidance on the path of interest rates,But the market will pay close attention to whether it makes it clear that the Fed is willing to restart raising interest rates if inflation cannot improve.Barclays believes that the probability of Warsh making such a statement is more than 50%, which will help strengthen the policy response function already implicit in current market pricing.
Meeting background: Both the bond market and the U.S. dollar are under pressure, why is this time different?
The Jackson Hole Annual Meeting is an annual economic policy symposium hosted by the Federal Reserve Bank of Kansas City that brings together global central bankers, policymakers, academics and economists every year. This conference was held from August 27th to 29th, with the theme of "Financial Innovation: Impact on Payment and Policy." Warsh will deliver a speech at 10 a.m. Eastern Time on August 28 (22:00 p.m. Beijing time on the 28th). Historically, there will be no public question and answer session after the speech.
Bank of America pointed out that the market pays special attention to Jackson Hole for two reasons:First, the seven-week interval between July and September interest rate meetings is the longest in the whole year. During this period, two non-agricultural and CPI data will be released. The market has always regarded this as a window for the Fed to announce its policy intentions in advance; second, market liquidity is thin in the summer, and any statement may trigger more severe price fluctuations.
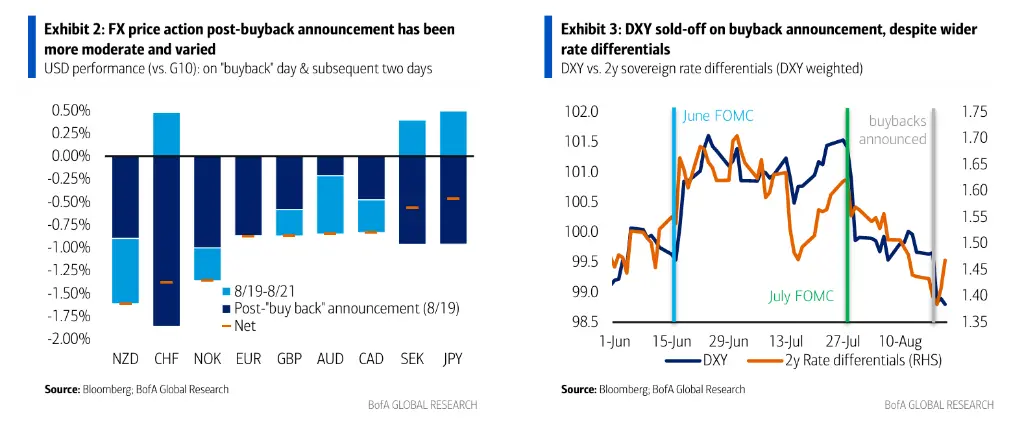
What makes this session unique is that both bond markets and the dollar are already in a fragile state. The U.S. Treasury Department announced last week that it would increase its efforts to repurchase long-term Treasury bonds. The dollar fell sharply on the day the news was announced. Bank of America believed that this move reflected the government's concern about the continued rise in long-term yields. Coupled with the previous "dovish" FOMC meeting in July and the weakening US economic data in August, the US dollar has suffered multiple negative effects.
Market expectations: Wash needs to "break" with his past self
Warsh has long resisted forward guidance. At the press conference of the July interest rate meeting, he said that the direction of the speech in Jackson Hole has not yet been determined, and listed two possibilities: first, focusing on macro and long-term issues such as productivity, demographic structure, and global economy; second, directly talking about the near-term policy direction from September to December.
Bank of America believes that the market's "forced palace" effect is changing this choice. The report quoted boxing champion Tyson's famous saying - "Everyone has a plan until they get slapped in the face" and pointed out that the bond market's continued "punch" on Wash has made it difficult for him to continue to avoid policy statements.
Bank of America strategists expect that Warsh will refer to the recent statements of Federal Reserve officials Paulson and Cook to clarify the policy response path under two scenarios: if the recent de-inflation process continues, the current stance will be maintained; if inflation remains high, he will make it clear that he is ready to restart interest rate increases. Bank of America believes that this kind of framework statement can effectively convey the policy response function without providing specific path commitments.
Barclays also held a similar judgment and pointed out that Warsh may also express his views on the forward guidance system itself - he has always criticized forward guidance for constraining policy flexibility and leading to historical policy mistakes, and established a special working group to evaluate this after taking office. In addition, Warsh may provide more information on the Fed's balance sheet policy, but in the current context of high long-term yields, any further reduction in portfolio duration needs to be extremely cautious.
Two Scenarios: Interest Rates, Curves and Differential Trends of the US Dollar
Bank of America gave two clear sets of market scenario predictions based on the content of Wash's speech.
Scenario 1: Warsh releases a signal to raise interest rates as scheduled. If it makes it clear that it is willing to restart interest rate hikes if inflation does not fall, Bank of America predicts that: the probability of an interest rate hike at the September FOMC meeting will rise from the current pricing of about 9 basis points to 12.5 basis points (i.e., 50 to 50 basis points); the total pricing range of this round of interest rate hike cycles will rise from about 40 basis points to close to 50 basis points; the nominal and real yield curves will tend to flatten; the US dollar is expected to recover some of its losses.
Scenario 2: Wash avoids policy statements. If the speech focuses on structural narratives such as productivity and AI-driven deinflation, or deliberately avoids recent policies on the grounds of "no forward guidance," Bank of America warns that the market may interpret it as a dovish signal, which will trigger a further steepening of the curve.The 30-year U.S. Treasury yield may quickly exceed 5.5%, and the U.S. dollar will also come under a new round of selling pressure.
Bank of America emphasized that the recent weakening of the U.S. dollar has given rise to a disturbing signal - after the buyback was announced, the U.S. dollar fell against the backdrop of widening interest rate differentials between the U.S. and other countries. This is a typical feature of risk premium expansion and reflects the market's potential concerns about "fiscal dominance" risks. If Warsh's statement further strengthens the outside world's doubts about the independence of the Fed's monetary policy, the "dollar devaluation" camp will gain more ammunition.
Historical Reference: Jackson Hole is not usually a market turning point, but this year may be an exception
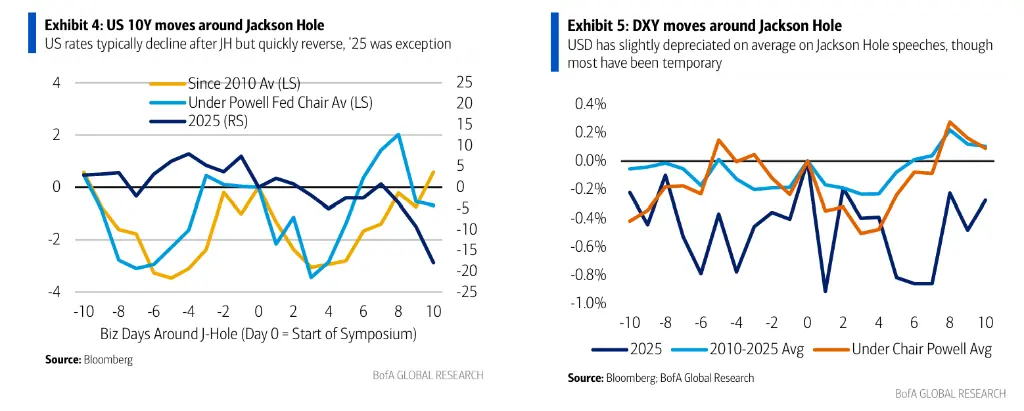
Judging from historical data, Jackson Hole's impact on the U.S. bond market is usually limited. According to Bank of America statistics, since 2010, the 10-year U.S. Treasury yield has tended to fall slightly after the annual meeting, but the above-mentioned trend has generally retraced within 10 trading days after the meeting. 2025 is an exception - the Federal Reserve's emphasis on the downside risks to the job market triggered a continued decline in yields and a significant weakening of the US dollar.
The same is true for the historical pattern of the foreign exchange market: the U.S. dollar tends to weaken slightly before and after annual meetings, but usually regains its losses in the following weeks; during Powell's tenure, the U.S. dollar's average reaction to Jackson Hole was relatively larger. 2022 is the most prominent case in recent years - at that time, Powell issued a tough anti-inflation speech, which directly triggered a sharp rise in interest rates and a strengthening of the US dollar.
Bank of America pointed out that this year's background is different from previous Jackson Holes: the Treasury Department has taken the lead in intervening in long-term yields, and the ball is now passed to Warsh's feet ("Bessent acted, Warsh now holds the ball"). At this special moment, if Wash fails to meet the market's minimum expectations for policy credibility, this annual meeting may have the most profound impact on the market in recent years.